When the Banks Ruled the World — and What That Lesson Owes the Age of the Platforms
Photo: John Robert McPherson, CC BY-SA 4.0, via Wikimedia Commons
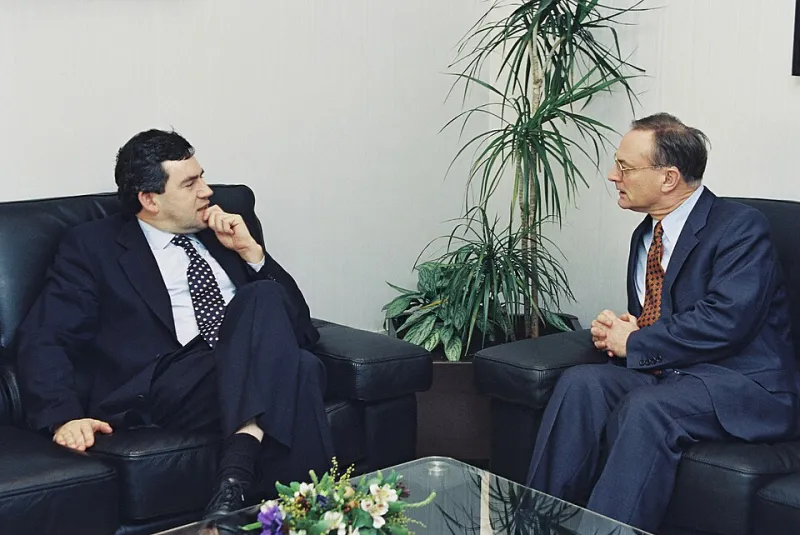
There is a photograph that ought to hang in every Treasury office in Whitehall. It shows Gordon Brown in the late 1990s, conferring with Alan Greenspan — the man whose easy-money consensus then governed the world. Brown listened, nodded, and then went home and did something the consensus said was impossible: he gave the Bank of England its independence and built a tripartite regulatory architecture designed for risks nobody could yet see.
The lesson of that decade was never written down, but it was learned all the same. When power concentrates, accountability must concentrate with it. In 2025, that lesson has a new address: not Threadneedle Street, but Palo Alto.
The New Untouchables
The five largest technology companies now hold a combined market value that dwarfs the annual GDP of every nation on earth except two. They set the terms of trade for small businesses, arbitrate public discourse, and hoard profits in jurisdictions that exist, in large part, to hoard them. When the digital services tax finally arrived in Britain — a policy whose intellectual DNA traces directly back to Brown's Treasury circle — the response from Washington was not debate but threat.
We have been here before. In the years before the crash, the City argued that any restraint on its freedom would simply relocate business to Frankfurt or New York. The argument was wrong then, and it is wrong now. Capital follows confidence, and confidence follows rules.
A Global Compact on Digital Wealth
What Brown's crash-era diplomacy — the coordinated bank recapitalisations, the G20 summits of 2009 — proved is that no nation can police a globalised industry alone. Taxation of platform profits is the same problem in new clothing. A digital services tax imposed unilaterally invites retaliation; a coordinated OECD framework invites compliance.
Labour should therefore argue for what we might call a global compact on digital wealth: common rules on profit-shifting, a minimum floor on effective tax rates for the largest platforms, and — crucially — a mandate for national competition authorities to unwind acquisitions made purely to extinguish competition. Brown understood that systemic risk is not an abstraction. Instagram buying its rivals was not entrepreneurship. It was consolidation, and we should have the honesty to name it.
From Market Failure to Market Design
Critics will say this is protectionism dressed as principle. It is the opposite. The pre-2008 settlement failed not because markets were regulated too heavily but because the regulators blinked at precisely the moment vigilance mattered. The platforms have enjoyed fifteen years of a regulator that blinked. British small publishers, independent retailers, and newsrooms have paid the price in advertising revenue siphoned to offshore accounts.
A Treasury-minded approach does not seek to strangle innovation. It seeks something simpler and more British: that companies making fortunes from British consumers contribute fairly to British public services, and that no firm is too big to challenge. That was the principle behind Brown's refusal to let the banks set their own capital rules. It should be the principle of a digital Treasury too.
The crash taught us that warnings ignored in good times become crises in bad ones. The platform economy is a good time — for a handful of people. Prudence, once again, means acting before the bill arrives.